Underpaid Insurance Claims
- UNDERPAID PROPERTY INSURANCE CLAIMS
Insurance Settlement Too Low? Let's Review What's Missing.
An Approved Claim Doesn’t Always Mean an Accurate Settlement.
Your insurance company may have accepted your property damage claim and issued a payment, but does the estimate account for everything necessary to repair your property?

- UNDERSTANDING UNDERPAID CLAIMS
Your Insurance Company's Estimate Is Not Always the Final Cost of Repairs.
When an insurance company evaluates property damage, it prepares an estimate based on the information available during the investigation. Some damages may be concealed, and other necessary repairs may not be identified or fully accounted for during the initial inspection.
Disagreements may also arise regarding repair methods, labor costs, material quantities, or the extent of damage to adjoining building components.
At OUTLX, we evaluate the insurance company’s estimate alongside the actual conditions of the property and the scope of work necessary for restoration.
Important to Understand
A settlement check that is lower than the estimated replacement cost does not automatically mean a claim was underpaid. Payments may reflect depreciation, deductibles, and other policy provisions.
Understanding these deductions is an important part of reviewing the settlement.
- COMMON REASONS INSURANCE CLAIMS ARE UNDERPAID
What Might Be Missing From Your Insurance Estimate?
At OUTLX, we handle the technical details so you can focus on your property and your future.
Overlooked Property Damage
Certain damages may not be visible during the initial inspection, including damage behind walls, ceilings, flooring, or other building materials.
Incomplete Repair Estimates
Estimates may omit necessary materials, labor, or construction activities, which can affect the overall cost of repairs.
Disagreements Over Repair Methods
Different repair methods can result in significantly different estimates. We evaluate whether the proposed repairs appropriately address the damage.
Material and Labor Pricing
Repair estimates depend on material costs, labor rates, quantities, and construction methods. These factors may warrant further evaluation.
Additional Damage Discovered During Repairs
Demolition and concealment can reveal damage that was not visible during the initial inspection.
Personal Property and Contents Valuation
Furniture, electronics, equipment, clothing, and other personal property may be missing from the inventory or valued differently from the actual loss.
- HOW OUTLX CAN HELP
A Detailed Review of Your Insurance Settlement
We handle the technical details so you can focus on your property and your future.
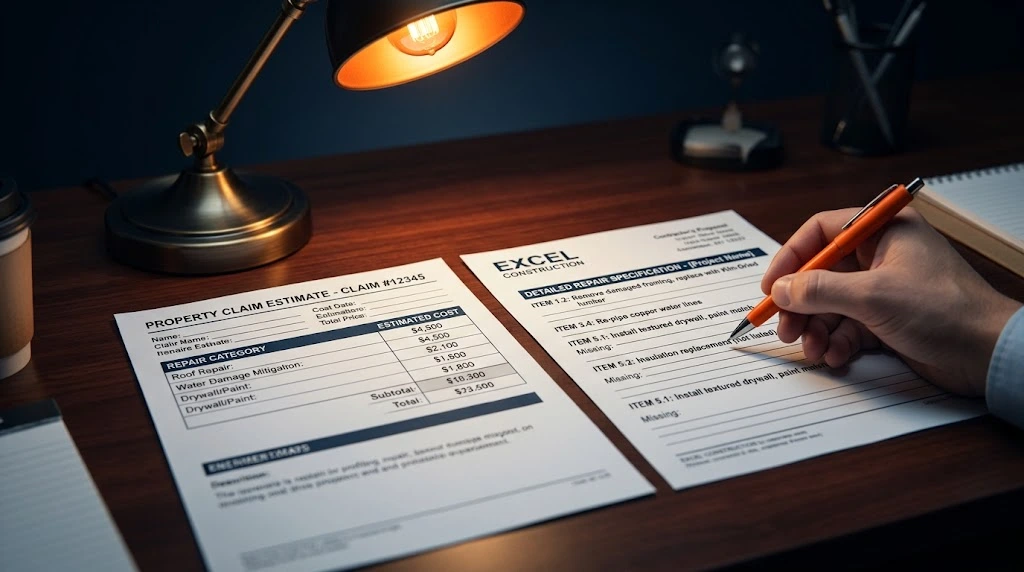
Review the Insurance Estimate
We review the insurance company’s estimate, claim documentation, and applicable policy provisions.
Inspect and Document the Property
When appropriate, we conduct an independent inspection to document the damage and identify conditions that may not have been accounted for.
Prepare a Detailed Estimate
Using Xactimate and supporting documentation, we develop a repair estimate reflecting the identified damages and necessary restoration work.
Present and Negotiate the Differences
We submit our findings and supporting documentation to the insurance company and communicate the differences in scope and valuation.
- WHAT AN UNDERPAID CLAIM CAN LOOK LIKE
Sometimes the Difference is in the Details
An insurance estimate is only as complete as the information used to prepare it. When additional damage is discovered or necessary repairs are omitted, those differences should be documented and presented for consideration.
| Initial Insurance Estimate May Include | Additional Findings May Reveal |
|---|---|
| Replace visible drywall | Concealed damage to insulation or framing |
| Replace damaged floor tile | Additional affected tile and adjoining finishes |
| Clean visible smoke damage | Soot contamination in concealed cavities |
| Repair damaged roofing | Additional sheathing or framing damage |
| Replace listed personal property | Missing inventory items or disputed valuations |
- RESIDENTIAL AND COMMERCIAL UNDERPAID CLAIMS
Underpaid Claims Affect Homes and Businesses Alike
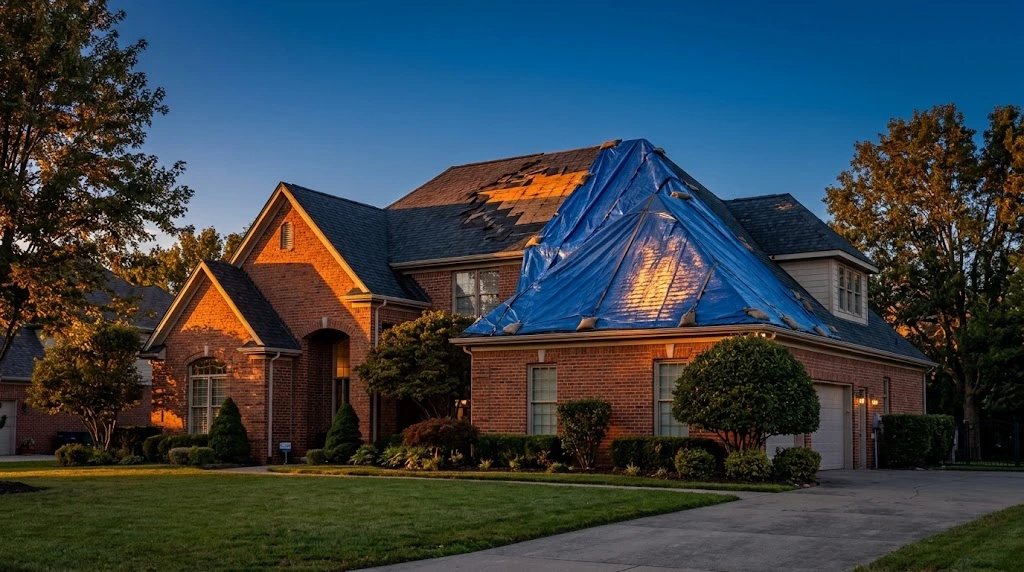
- RESIDENTIAL
Residential Insurance Claims
An insufficient settlement can leave homeowners facing unexpected repair expenses. OUTLX assists homeowners with evaluating these differences and preparing documentation to support their claims.
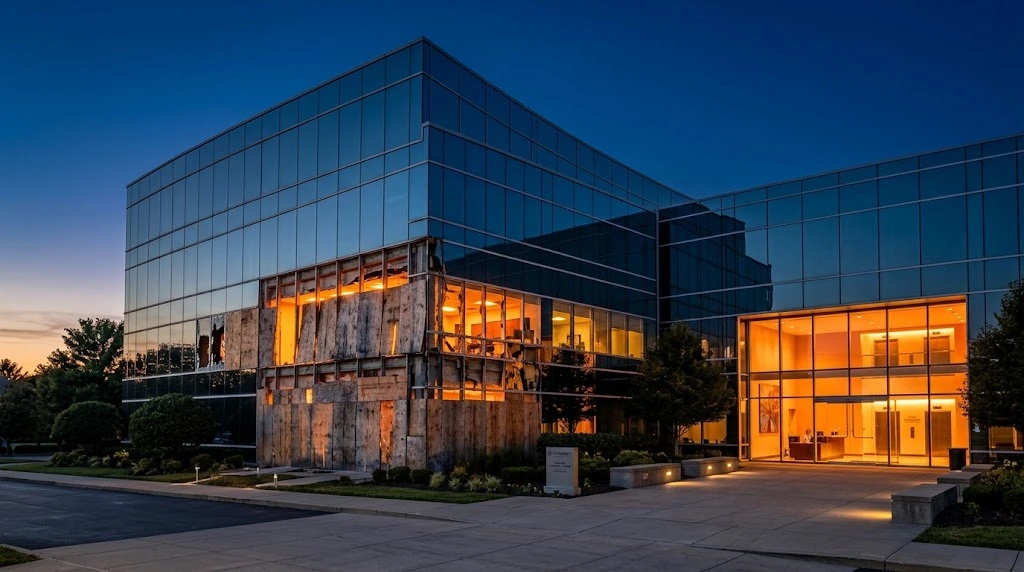
- COMMERCIAL
Commercial Insurance Claims
Commercial property losses often involve complex structures, specialized materials, and larger repair scopes. OUTLX assists commercial property owners with evaluating these differences and documenting disputed repair costs.
- WHAT CAN YOU DO IF YOUR INSURANCE SETTLEMENT IS TOO LOW?
Understanding Your Options
Professional representation may be beneficial at several stages of the insurance claims process.
Request a Supplemental Estimate
Additional documentation and newly discovered damages may support a request for reconsideration.
Obtain an Independent Assessment
A licensed public adjuster can assist with inspecting the damage, preparing estimates, and presenting claim documentation.
Consider the Appraisal Process
Some policies provide an appraisal process for resolving disagreements involving the amount of loss.
Seek Legal Guidance When Appropriate
Policy interpretation or coverage disputes may require assistance from an attorney.
Yes. Receiving a payment does not necessarily mean the claim is closed or that you have accepted the settlement as final. If you discover additional damage or believe the estimate was incomplete, you can typically request a supplemental payment or dispute the amount.
This is very common. Insurance companies use their own estimating software (like Xactimate) and pricing. A contractor's estimate might include higher material costs, different repair methods, or code upgrades that the insurance company did not account for. A public adjuster can help bridge this gap by presenting detailed documentation to the insurer.
Absolutely. It is very common to find hidden damage (like mold behind drywall or rotted framing) once repairs begin. This is called "supplementing" the claim. You will need to document the newly discovered damage with photos and updated estimates and submit them to your insurance company.
Replacement Cost Value (RCV) is what it costs to replace the damaged property with new materials of similar quality. Actual Cash Value (ACV) is the replacement cost minus depreciation (the age and wear of the item). If your policy is ACV, your initial check will be lower.