- TEXAS WIND & HAIL DAMAGE CLAIMS
Wind & Hail Damage Insurance
Claims in Texas
- Storm Damage Isn't Always Visible From the Ground.
Severe thunderstorms, high winds, and hail can damage roofing systems, exterior building components, and interior finishes. While some damage is immediately visible, other conditions require a closer inspection to determine the full extent of the loss.
At OUTLX Public Adjusters, we represent homeowners and commercial property owners throughout Texas, helping document storm-related damage, prepare detailed repair estimates, and navigate the insurance claims process.
- UNDERSTANDING WIND & HAIL DAMAGE
Not All Storm Damage Looks the Same
Residential Roofing Systems
Wind and hail can affect asphalt shingles, metal roofing, tile, and other residential materials. Damage may include granule loss, material fractures, impact damage, or compromised components.
Commercial Roofing Systems
Commercial roofs may involve modified bitumen, TPO, EPDM, metal, and other specialized assemblies. Each system requires an appropriate inspection and evaluation of the observed damage.
Exterior Building Components
Storm damage may extend beyond the roof to gutters, flashing, siding, stucco, windows, doors, fencing, and other exterior components.
Interior Storm Damage
When a storm compromises the building envelope, water may enter and damage ceilings, insulation, drywall, flooring, and interior finishes. Determining the source and extent of intrusion is important when evaluating the claim.
- WIND DAMAGE BEYOND TORN OR MISSING SHINGLES
Wind Damage Can Involve More Than Torn, Creased, or Missing Shingles
Insurance assessments often focus on shingles that are visibly torn, creased, or missing. However, wind-related damage can also involve unsealed tabs, sealant separation, and material transfer, which may indicate that the adhesive bond was previously established and later compromised by wind forces.
At OUTLX, we evaluate the physical evidence, including material transfer, sealant integrity, the distribution of affected shingles, and other relevant conditions to determine whether the damage is consistent with storm-related wind forces.
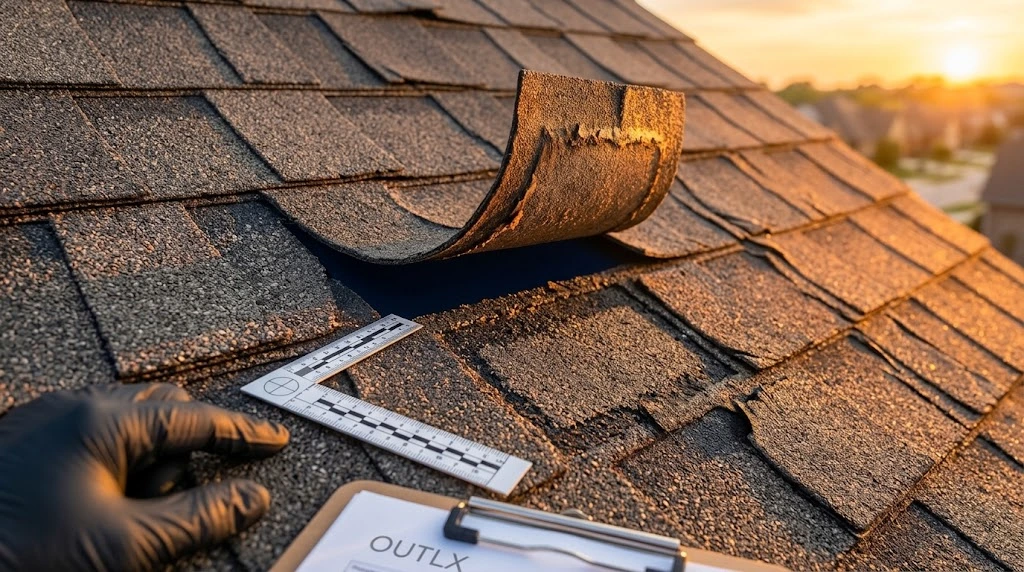
Unsealed Shingle Tab With Material Transfer
- COMMERCIAL HAIL DAMAGE TO TPO ROOFING
Hail Damage to TPO Roofs Isn't Always Visible on the Surface
Hail can affect TPO roofing systems even when surface damage is not immediately visible. Significant impacts may fracture the membrane or damage the underlying polyisocyanurate (ISO) insulation, including the facer, which may not be apparent during a visual inspection.
At OUTLX, we understand the importance of evaluating the entire roofing assembly and, when appropriate, recommending additional inspection or testing to determine the extent of damage.
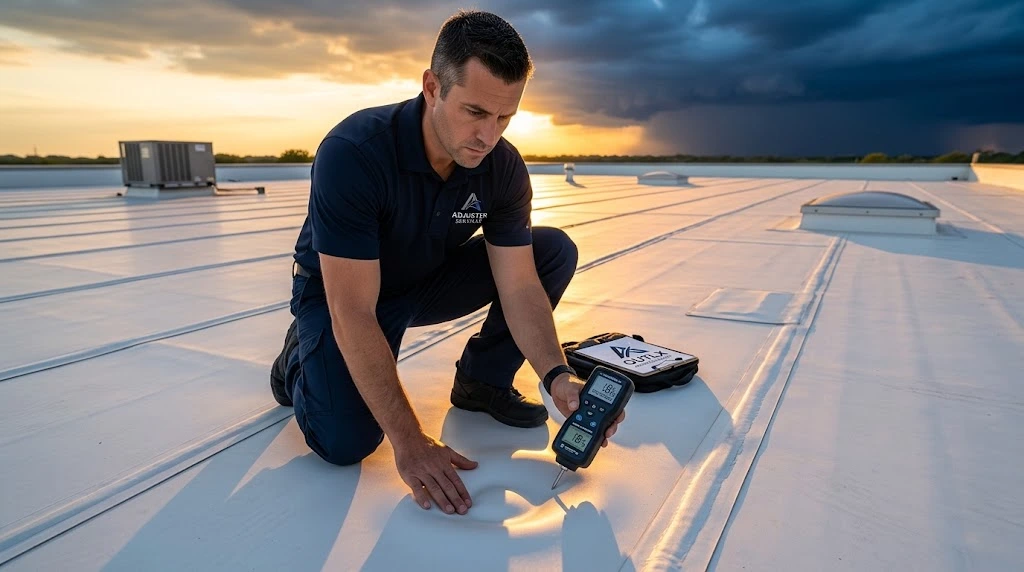
Hail Impact to TPO Membrane
Surface damage may be minimal while underlying components may be affected.
- ON-SITE ROOF INSPECTIONS
See How We Inspect Commercial TPO Roofing Systems
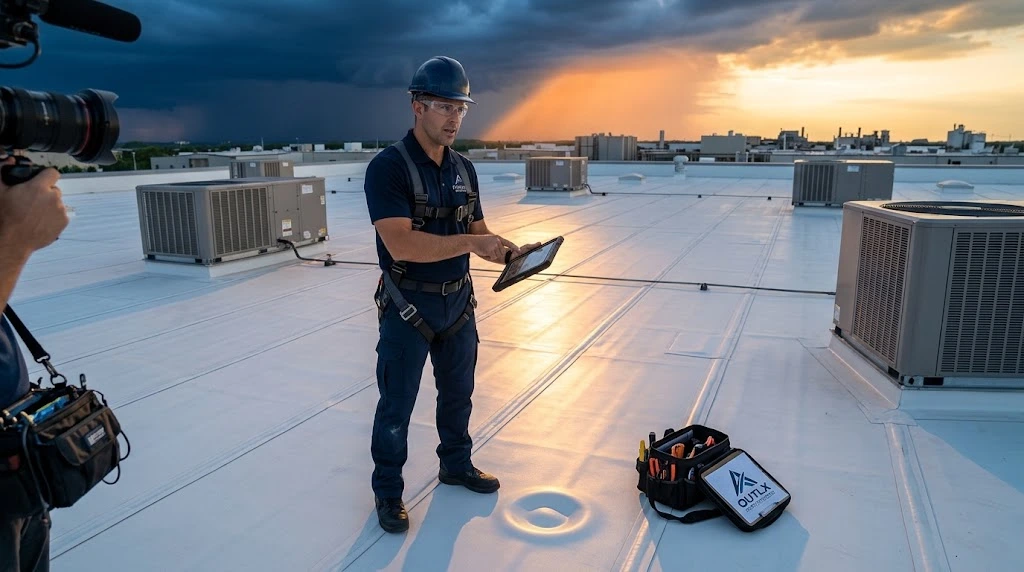
A Closer Look at TPO Roof Inspections
In this video, we inspect a commercial TPO roofing system and discuss types of storm-related damage, including hail impacts, membrane conditions, and underlying insulation concerns.
OUTLX takes a detailed, methodical approach to evaluate commercial roofing systems and document the conditions that should be considered in an insurance claim.
- ADVANCED INSPECTION TECHNOLOGY
Infrared Drone Inspections for Hidden Roof Damage
Not all roofing damage can be identified through a conventional visual inspection. Our team uses infrared-equipped drones to help detect thermal anomalies that may indicate moisture within the roofing assembly.
This technology can be especially valuable for large commercial roofs, where hidden damage may extend beyond visible surface inspection or testing findings can help guide additional investigation and testing when evaluating a disputed claim.
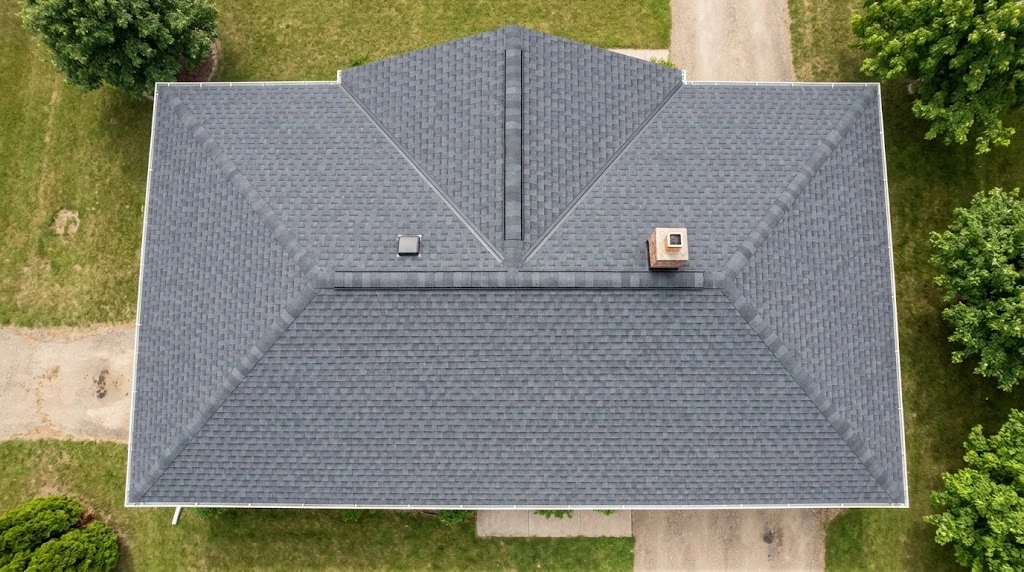
Standard Aerial View
Roof surface with no visible damage.

Infrared Thermal Image
RESIDENTIAL & COMMERCIAL STORM CLAIMS
Representing Homeowners and Commercial Property Owners

Residential Wind & Hail Claims
Storm damage to a home can involve more than the roof covering. OUTLX assists homeowners with evaluating roof, exterior, and interior damage, documenting the loss, and preparing the repairs necessary to support their claims.
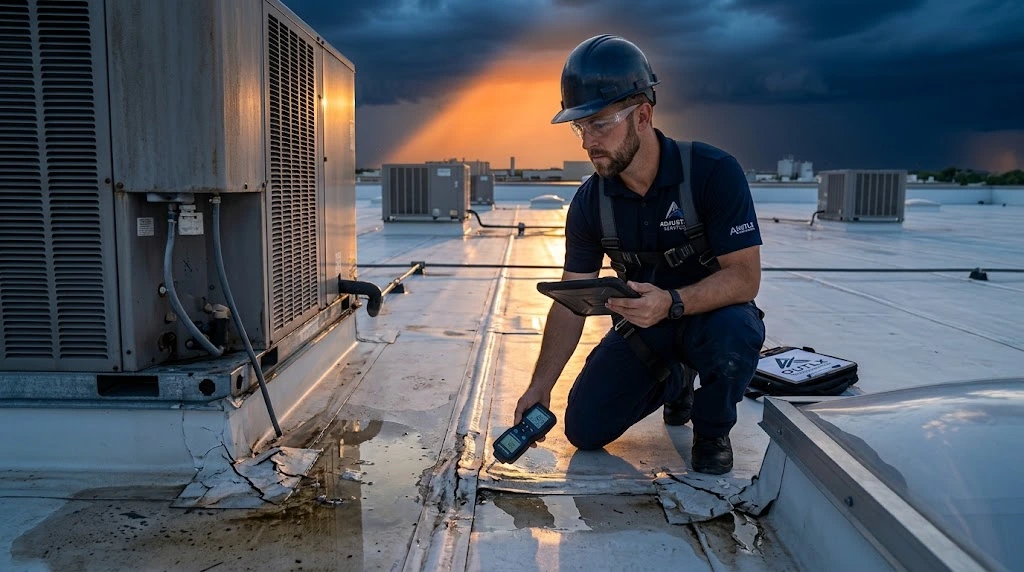
Commercial Flood Damage Claims
UNDERSTANDING YOUR WIND & HAIL COVERAGE
Your Policy Determines How Storm Damage Is Evaluated and Paid
01
Wind & Hail Deductibles
Some policies contain separate deductibles for wind or hail damage, which may be calculated as a percentage of the property's insured value.
02
Replacement Cost vs. Actual Cash Value
Policies may provide replacement cost coverage or calculate payments using actual cash value or specific roof payment schedules.
03
Coastal Windstorm Coverage
Certain coastal properties may have separate windstorm insurance through the Texas Windstorm Insurance Association (TWIA) rather than a standard policy.
04
Wind-Driven Rain vs. Flooding
Water entering through a storm-created roof opening may be covered, while flooding generally requires separate flood insurance.
HOW OUTLX HANDLES FLOOD DAMAGE CLAIMS
A Detailed Approach to Wind & Hail Losses
01
Property Inspection
We inspect the property, evaluate the visible damage, and document relevant conditions.
02
Damage Documentation
We document the observed damage and prepare detailed estimates supported by photos, measurements, and technical documentation.
03
Insurance Estimate Review
We review the insurance company's findings and scope to identify any discrepancies.
04
Claim Presentation & Negotiation
We present our findings and work with the insurance company to resolve disputed claim amounts.
Yes. In Texas, you can hire a public adjuster at any point during the claims process. However, it is highly recommended to hire one before you sign a final settlement or release with your insurance company. A public adjuster can review the initial estimate, identify missing damages, and negotiate on your behalf before the claim is closed.
No. A public adjuster works exclusively for you (the policyholder). They are licensed and regulated by the Texas Department of Insurance, but they are independent contractors hired to represent your best interests. An insurance company has its own "staff adjuster" or "independent adjuster" whose job is to protect the insurance company's financial interests.
No. By law, a public adjuster cannot guarantee a specific settlement amount or promise a specific outcome. Every claim is unique and subject to the terms of your policy. However, a public adjuster's goal is to ensure that all covered damages are fully identified and documented, which often results in a more accurate and higher settlement offer than the initial estimate.
Public adjusters typically work on a contingency fee basis, meaning they do not get paid unless you get paid. In Texas, the standard fee is a percentage of the final settlement amount (usually between 10% and 15%, depending on the complexity of the claim). You pay nothing out of pocket upfront.